
DEAL ROOM
PRIVATE VIEW
REVENUE (LTM-2025,COMBINED)
$ 10,757,532
ANNUAL REVENUE
$10,757,532
COMBINED EBITDA (2025)
$ 1,340,614
EST.ADJ EBITDA/SDE (2025)
$1,540,000 - $1,660,000+
SELLER EXPECTATION
$12.7M - $15.5M
THE OPPORTUNITY
Acquisition Price
$2.25M
2025 ADJ.EBITDA
$884K
BUYER EQUITY
$500K
IMPLIED MULTIPLE
$2.5K
DEAL SNAPSHOT
At-a-glance summary of the opportunity. All financial figures are document-verified unless noted.
OPPORTUNITY HIGHLIGHTS
• Vertically integrated platform — construction, asphalt plant, two rock quarries, and ready-mix concrete operating as a unified supply chain with built-in margin advantages.
• 35-year operating history with strong regional brand, loyal customer base, experienced site supervisors, and low competition in Central Missouri markets.
• Significant seller add-backs (retiring founder's $200K draw + depreciation) produce materially higher cash earnings than reported net income.
Executive Summary
This business is a specialized provider of waterfront restoration, shoreline engineering, and land development services based in West Michigan. Operating for over 17 years, the company has established a premier reputation in a highly regulated and permit-heavy market. It specializes in protecting and restoring high-value Lake Michigan and inland lake waterfront properties, commanding premium pricing due to its technical expertise and regulatory compliance capabilities. With a strong operational rebound in 2026, the company is demonstrating exceptional financial performance, supported by a loyal, skilled workforce and a robust pipeline of future projects.
Company History
Founded in 2009 by the current owners, the company has grown into a dominant niche player in the shoreline construction industry. Over nearly two decades, it has evolved from general landscape work to sophisticated erosion control, slope stabilization, and structural work necessitated by the unique geography of the Great Lakes region. The firm has successfully navigated various economic cycles and regulatory environments, cementing its position as a go-to contractor for high-net-worth property owners.
COMPANY OVERVIEW
• Company Name: Confidential — available upon NDA execution.
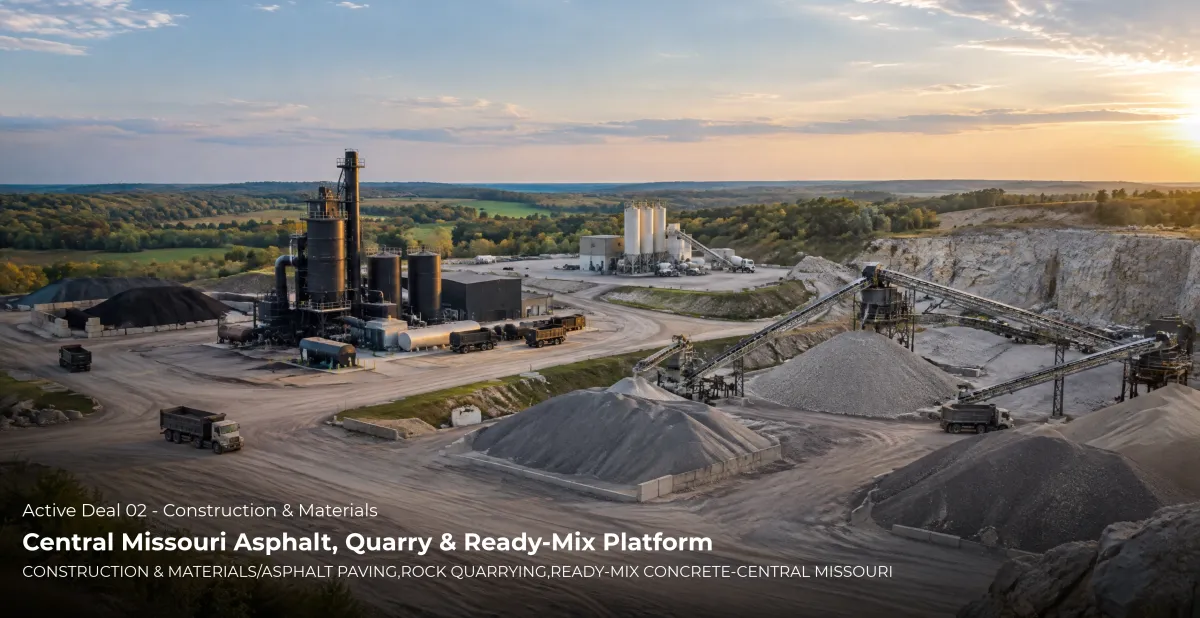
• Industry / Subcategory: Construction & Materials / Asphalt Paving, Rock Quarrying, Ready-Mix Concrete.
• Location: Central Missouri (four operating locations).
• Years in Business: 35 years (founded 1991).
• Business Type: S-Corp + LLCs (four integrated entities).
• Website: Available upon NDA execution.
TRANSACTION DETAILS
• Seller Expectation: $12.7M – $15.5M (combined, all 4 entities; see Assets for asset breakdown).
• Deal Structure: Asset sale preferred; all four entities ideally sold together due to supply chain integration.
• Reason for Sale: Owner (age 48) exploring monetization; no urgency — open to extended transition.
• Timeline to Sell: Flexible — 6–18 months or longer; owner open to multi-year consulting/transition role.
TEAM & OWNER
Employees: ~40–50 total across all entities (20–26 construction co.; 6 primary quarry; 4 secondary quarry; 7 concrete; 2–3 mechanics shared).
Owner Involvement: Active owner — manages all four companies daily; handles estimating (~40%), strategic decisions, pricing, and vendor relationships.
TEAM & OWNER
Employees: ~40–50 total across all entities (20–26 construction co.; 6 primary quarry; 4 secondary quarry; 7 concrete; 2–3 mechanics shared). Owner Involvement: Active owner — manages all four companies daily; handles estimating (~40%), strategic decisions, pricing, and vendor relationships.
DEAL HIGHLIGHTS
OPERATING HISTORY
35 years
(founded 1991)
LOCATION
Central Missouri
(four operating locations)
BUSINESS TYPE
S-Corp + LLCs
(four integrated entities)
EMPLOYEES
approximately 40-50 employees
across all entities
FINANCIAL PERFORMANCE
YEAR
REVENUE
EBITDA/SDE
2023
$ 13,085,984
$ 1,902,298
2024
$ 8,738,315
$ 531,285
2025
$ 10,757,532
$ 1,340,614
All figures are document-verified from entity-level P&Ls and balance sheets.
Combined totals represent all four operating entities.
FY 2025 Combined Net Income: $518,224
EBITDA Margin: 12.5%
Net Profit Margin: 4.8%. EBITDA = Net Income + Depreciation + Interest Expense.
All figures are document-verified from entity-level P&Ls and balance sheets. Combined totals represent all four operating entities.
FY 2025 Combined Net Income: $518,224; EBITDA Margin: 12.5%; Net Profit Margin: 4.8%. EBITDA = Net Income + Depreciation + Interest Expense.
FINANCIAL PERFORMANCE
YEAR
2023
REVENUE
$ 13,085,984
EBITDA/SDE
$ 1,902,298
YEAR
2024
REVENUE
$ 8,738,315
EBITDA/SDE
$ 531,285
YEAR
2025
REVENUE
$ 10,757,532
EBITDA/SDE
$ 1,340,614
All figures are document-verified from entity-level P&Ls and balance sheets.
Combined totals represent all four operating entities.
FY 2025 Combined Net Income: $518,224; EBITDA Margin: 12.5%
Net Profit Margin: 4.8%.
EBITDA = Net Income + Depreciation + Interest Expense.
The Opportunity
This is an established HVAC business with maintenance agreements, service work, and replacement revenue. The company has operated since 2005, employs 11 people, and has a meaningful commercial customer base. The seller is expected to provide financing and transition support, which helps keep the buyer’s cash into the deal at $500K under the proposed structure.
The business is being offered at roughly 2.5x the reported 2025 adjusted EBITDA. Possible operating levers include hiring technicians, growing commercial work, improving digital lead flow, adding plumbing, and expanding into nearby markets.
BUYER EQUITY
$500K
SELLER NOTE
$500K
BANK / SBA
$1.25M
What Needs to Be Proven
Earnings Quality
The reported adjusted EBITDA needs to tie back to tax returns, general ledger activity, bank statements, and every add-back.
Owner Replacement
The current owner handles estimating, sales, relationships, and management. The cost to replace those duties must be underwritten.
downside coverage
Test customer concentration, normal CapEx, working capital, taxes, and debt service under lower-revenue cases.
COMPLETE SOURCE BRIEF
ENTITY-LEVEL FINANCIAL DETAIL - FY 2025
• Asphalt & Construction Co.: Revenue $6,459,218; Net Income $154,879; EBITDA $549,257; EBITDA Margin 8.5%.
• Primary Rock Quarry: Revenue $1,494,201; Net Income $208,907; EBITDA $448,871; EBITDA Margin 30.0%.
• Secondary Rock Quarry: Revenue $991,846; Net Income $11,838; EBITDA $162,764; EBITDA Margin 16.4%.
• Ready-Mix Concrete Plant: Revenue $1,812,267; Net Income $142,600; EBITDA $179,722; EBITDA Margin 9.9%.
• Combined Total: Revenue $10,757,532; Net Income $518,224; EBITDA $1,340,614; EBITDA Margin 12.5%.
HISTORICAL REVENUE - ASPHALT & CONSTRUCTION
(LARGEST ENTITY)
• FY 2022: Revenue $7,047,237; Net Income $303,072; EBITDA $918,183; EBITDA Margin 13.0%.
• FY 2023: Revenue $8,788,871; Net Income $623,237; EBITDA $1,133,025; EBITDA Margin 12.9%.
• FY 2024: Revenue $4,341,092; Net Income ($550,143); EBITDA ($106,023); EBITDA Margin N/M.
• FY 2025: Revenue $6,459,218; Net Income $154,879; EBITDA $549,257; EBITDA Margin 8.5%.
ENTITY-LEVEL FINANCIAL DETAIL -
FY 2025
• Asphalt & Construction Co.: Revenue $6,459,218; Net Income $154,879; EBITDA $549,257; EBITDA Margin 8.5%.
• Primary Rock Quarry: Revenue $1,494,201; Net Income $208,907; EBITDA $448,871; EBITDA Margin 30.0%.
• Secondary Rock Quarry: Revenue $991,846; Net Income $11,838; EBITDA $162,764; EBITDA Margin 16.4%.
• Ready-Mix Concrete Plant: Revenue $1,812,267; Net Income $142,600; EBITDA $179,722; EBITDA Margin 9.9%.
• Combined Total: Revenue $10,757,532; Net Income $518,224; EBITDA $1,340,614; EBITDA Margin 12.5%.
HISTORICAL REVENUE - ASPHALT & CONSTRUCTION (LARGEST ENTITY)
• FY 2022: Revenue $7,047,237; Net Income $303,072; EBITDA $918,183; EBITDA Margin 13.0%.
• FY 2023: Revenue $8,788,871; Net Income $623,237; EBITDA $1,133,025; EBITDA Margin 12.9%.
• FY 2024: Revenue $4,341,092; Net Income ($550,143); EBITDA ($106,023); EBITDA Margin N/M.
• FY 2025: Revenue $6,459,218; Net Income $154,879; EBITDA $549,257; EBITDA Margin 8.5%.
ADD-BACKS & ADJUSTED EARNINGS
• Reported Combined EBITDA (2025): $1,340,614.
• Verified Add-Back: Retiring Founder's Compensation — $200,000. Fully retired founder draws salary, vehicle, fuel, and insurance through the business; 100% add-back post-sale.
• Verified Add-Back: Depreciation (Non-Cash) — already included in EBITDA above.
•Potential Add-Back: Owner Salary Normalization — ~$50,000–$100,000.
Owner draws below market for his role; replacement GM would cost $200K+. Partial add-back warranted.
• Potential Add-Back: Entertainment / Travel — ~$15,000–$25,000/yr. Company-funded team events; discretionary.
• Potential Add-Back: Donations & Scholarships — ~$15,000–$20,000/yr.
Community goodwill; discretionary.
• Potential Add-Back: Year-End Tax Management — Variable. Owner manages net income toward zero; buyer should normalize.
• Estimated Adjusted EBITDA / SDE (2025): ~$1,540,000 – $1,660,000+.
FINANCIAL COMMENTARY
Revenue across the enterprise has ranged from $8.7M (2024, election year) to $13.1M (2023, banner year), with 2025 tracking back toward $10.8M combined.
The 2024 trough was driven by two documented factors: (1) election years are consistently weak for public infrastructure spending in this market — municipalities hold funds pending political transitions — and (2) the construction company executed internal asset transfers between entities to reconcile historical intercompany loans, creating a $400K paper loss offset by gains in the quarry entities.
Net income as reported understates true cash earnings significantly. The business actively manages toward minimal taxable income via bonus distributions, accelerated depreciation, and equipment purchases. The confirmed $200K annual draw by the retired founding operator represents a clean, fully recoverable add-back post-acquisition.
The quarries — particularly the primary location — are the highest-quality EBITDA contributors when normalized. Primary quarry 2025 reported EBITDA of $448,871 (30% margin) on $1.49M revenue, though $221,803 of that is depreciation on new equipment purchased in 2025. Both quarries are cash-flow positive. The secondary quarry is showing margin compression due to depreciation on new equipment.
Discrepancy Note: All verbal figures provided by the seller during the initial call align with audited P&L documents provided. No material discrepancies were identified.
Employees
The company employs 7 field crew members who are cross-trained in slope restoration, shoreline construction, carpentry, and equipment operation. The tenure and loyalty of this workforce are key assets to the business.
Owner Involvement
The owner is currently deeply embedded in all aspects of the business, including sales, site visits, estimating, and project design. The business is currently highly owner-dependent, but this is a bounded risk given the company’s strong systems and the owner’s commitment to a 6-month transition period. The ideal buyer is an individual with strong project management and business operations skills who is willing to learn the technical and regulatory aspects of the industry.
ADD-BACKS & ADJUSTED EARNINGS
• Reported Combined EBITDA (2025): $1,340,614.
• Verified Add-Back: Retiring Founder's Compensation — $200,000. Fully retired founder draws salary, vehicle, fuel, and insurance through the business; 100% add-back post-sale.
• Verified Add-Back: Depreciation (Non-Cash) — already included in EBITDA above.
• Potential Add-Back: Owner Salary Normalization — ~$50,000–$100,000. Owner draws below market for his role; replacement GM would cost $200K+. Partial add-back warranted.
• Potential Add-Back: Entertainment / Travel — ~$15,000–$25,000/yr. Company-funded team events; discretionary.
• Potential Add-Back: Donations & Scholarships — ~$15,000–$20,000/yr. Community goodwill; discretionary.
• Potential Add-Back: Year-End Tax Management — Variable. Owner manages net income toward zero; buyer should normalize.
• Estimated Adjusted EBITDA / SDE (2025): ~$1,540,000 – $1,660,000+
FINANCIAL COMMENTARY
Revenue across the enterprise has ranged from $8.7M (2024, election year) to $13.1M (2023, banner year), with 2025 tracking back toward $10.8M combined.
The 2024 trough was driven by two documented factors:
(1) election years are consistently weak for public infrastructure spending in this market — municipalities hold funds pending political transitions — and (2) the construction company executed internal asset transfers between entities to reconcile historical intercompany loans, creating a $400K paper loss offset by gains in the quarry entities.
Net income as reported understates true cash earnings significantly. The business actively manages toward minimal taxable income via bonus distributions, accelerated depreciation, and equipment purchases. The confirmed $200K annual draw by the retired founding operator represents a clean, fully recoverable add-back post-acquisition.
The quarries — particularly the primary location — are the highest-quality EBITDA contributors when normalized. Primary quarry 2025 reported EBITDA of $448,871 (30% margin) on $1.49M revenue, though $221,803 of that is depreciation on new equipment purchased in 2025. Both quarries are cash-flow positive. The secondary quarry is showing margin compression due to depreciation on new equipment.
Discrepancy Note: All verbal figures provided by the seller during the initial call align with audited P&L documents provided. No material discrepancies were identified.
REVENUE BREAKDOWN
• Asphalt & Construction (~60% of combined revenue): Primary revenue driver. Services include asphalt paving of city streets, county roads, commercial parking lots, private driveways, new subdivisions, and government/public projects (prevailing wage). Asphalt plant serves internal production.
• Primary Rock Quarry (~14%): Limestone aggregate at ~$14/ton average. FY2025 revenue: $1,494,201. Volume growing — 160,000+ tons in 2025. Serves internal use, external contractors, and agricultural customers.
• Secondary Rock Quarry (~9%): ~$1M/year; ~100,000 tons/year. Agricultural customers and local contractors. Stable, growing slowly.
• Ready-Mix Concrete Plant (~17%): Growing from $1.63M (2023) to $1.81M (2025). 12 mixer trucks. Serves residential, commercial, and agricultural customers in a growing regional market.
• Customer Type: B2B / Government (dominant); Private Commercial; Agricultural; Residential.
• Concentration Risk: Low to Moderate — diversified across public projects, commercial, agricultural, and residential. Government project work creates baseline demand regardless of economic cycle.
• Recurring Revenue: Government infrastructure spending and repeat quarry/concrete customers provide consistent annual baseline.
• Seasonality: Asphalt paving season runs ~May 1 through late November. Q1 of each year shows minimal revenue with full fixed costs. Quarries and concrete plant run year-round and offset winter gaps.
CUSTOMERS & SALES
Lead Sources: Government bid systems (public project process), repeat relationships (35+ years of project delivery), word-of-mouth through community engagement, billboards and website, community sponsorships and charitable giving programs.
Sales Process: Public projects are competitively bid. The owner personally handles ~40% of estimating to maintain market pricing intelligence; other estimators handle remaining volume. Private/commercial work uses direct quotes from field visits with relationship-driven conversion.
Quarry/concrete materials are primarily inbound; remote-operated scale houses allow one attendant to manage both quarry locations simultaneously via camera and ticketing system.
Repeat Business: Very high across all entities. Government clients return annually for infrastructure maintenance. Quarry and concrete customers are largely repeat purchasers. Customer retention through ownership transitions is expected if service standards are maintained.
REVENUE BREAKDOWN
• Asphalt & Construction (~60% of combined revenue): Primary revenue driver. Services include asphalt paving of city streets, county roads, commercial parking lots, private driveways, new subdivisions, and government/public projects (prevailing wage). Asphalt plant serves internal production.
• Primary Rock Quarry (~14%): Limestone aggregate at ~$14/ton average. FY2025 revenue: $1,494,201. Volume growing — 160,000+ tons in 2025. Serves internal use, external contractors, and agricultural customers.
• Secondary Rock Quarry (~9%): ~$1M/year; ~100,000 tons/year. Agricultural customers and local contractors. Stable, growing slowly.
• Ready-Mix Concrete Plant (~17%): Growing from $1.63M (2023) to $1.81M (2025). 12 mixer trucks. Serves residential, commercial, and agricultural customers in a growing regional market.
• Customer Type: B2B / Government (dominant); Private Commercial; Agricultural; Residential.
• Concentration Risk: Low to Moderate — diversified across public projects, commercial, agricultural, and residential. Government project work creates baseline demand regardless of economic cycle.
• Recurring Revenue: Government infrastructure spending and repeat quarry/concrete customers provide consistent annual baseline.
• Seasonality: Asphalt paving season runs ~May 1 through late November. Q1 of each year shows minimal revenue with full fixed costs. Quarries and concrete plant run year-round and offset winter gaps.
CUSTOMERS & SALES
Lead Sources: Government bid systems (public project process), repeat relationships (35+ years of project delivery), word-of-mouth through community engagement, billboards and website, community sponsorships and charitable giving programs.
Sales Process: Public projects are competitively bid. The owner personally handles ~40% of estimating to maintain market pricing intelligence; other estimators handle remaining volume. Private/commercial work uses direct quotes from field visits with relationship-driven conversion. Quarry/concrete materials are primarily inbound; remote-operated scale houses allow one attendant to manage both quarry locations simultaneously via camera and ticketing system.
Repeat Business: Very high across all entities. Government clients return annually for infrastructure maintenance. Quarry and concrete customers are largely repeat purchasers. Customer retention through ownership transitions is expected if service standards are maintained.
OPERATIONS
Employee Overview: ~40–50 total employees across all entities. Construction company: 20–26 (seasonal, some farm in winter). Primary quarry: 6 FT. Secondary quarry: 4 FT. Concrete plant: 7 FT. Shared mechanics: 2 FT + 1 PT (recently retired, works 2–3 days/week by choice). Scale house operated remotely by single attendant covering both quarry locations.
Compensation: Supervisors earn six figures. Prevailing wage projects pay laborers $35–$55/hour and operators up to $68/hour. Company pays above-market; year-end bonuses distributed in strong years.
Key Operators: The Primary Quarry Lead is a multi-discipline expert — asphalt plant operator, electrician, welder, and fabricator — described as the brains of the operation, with high retention likelihood. The Primary Quarry Operations Lead keeps production moving and people organized. The Secondary Quarry Manager runs day-to-day production and personnel. Two Construction Supervisors run day-to-day operations of all construction crews.
Business Dependency on Owner: Moderate. Key risks if owner departs include estimating/bidding (~40% done by owner), cross-entity supply chain coordination, key government and vendor relationships, and pricing strategy. Mitigation: Owner open to multi-year transition/consulting; supervisors run each site independently; strong operational team in place.
Systems & SOPs: QuickBooks-based accounting, entity-level. Remote scale house management system (camera + ticketing). Estimating mix of owner-led and estimator-supported. No formal CRM identified. SOPs are largely informal — opportunity for buyer to implement standardization during transition.
ASSETS
• Asphalt & Construction equipment: ~$2,500,000 (asphalt plant, pavers, rollers, dump trucks, service trucks, trailers).
• Primary Rock Quarry equipment: ~$1,000,000 (crusher, screens, loaders, quarry equipment). New cone crusher added 2025. Three-phase electric infrastructure established.
• Secondary Rock Quarry equipment: ~$1,000,000 (crusher, loaders, quarry equipment).
• Concrete Plant: 12 mixer trucks ($40K–$70K each); 2 loaders (~$30K each); plant/controls (~$200K). Total hard equipment: ~$800K–$900K per seller.
• Concrete Plant Property (Owned): 18 acres. Estimated value $450K–$540K at ~$25K–$30K/acre. Private well. County jurisdiction only (less restrictive). Seller price for concrete entity (land + equipment + business): $3.2M–$3.5M.
• Primary Quarry Lease: 185 years remaining. 3% royalty per ton sold. Exceptional long-term asset.
• Secondary Quarry Lease: 19 years remaining. 3% royalty per ton. Extension actively being pursued — critical milestone before sale.
• Main HQ: NOT included. Family land will not transfer. Alternative office space available at other company locations.
• Inventory as of 12/31/25 balance sheet: Primary Quarry Rock Inventory $47,364; Secondary Quarry Rock Inventory $40,576; Asphalt Inventory $151,850.
GROWTH OPPORTUNITIES
• State Highway Contract Access: Current owner avoids MoDOT/state work. Asphalt plant is capable. The I-70 widening project (4 to 6 lanes, Kansas City to St. Louis, underway through 2032–2034) represents a generational infrastructure spend in the company's region. A buyer willing to manage state contract compliance could access this market.
• Asphalt Material External Sales: Plant currently produces for internal use only. Selling mix to other contractors is untapped revenue. Plant has unused summer capacity.
• Quarry Volume Growth: Both quarries show year-over-year volume growth. With large contractors committed to regional infrastructure projects, external aggregate demand is rising.
• Pricing Optimization & Digital Marketing: No CRM or digital marketing exists. Data-driven pricing and systematic customer acquisition could drive incremental revenue without proportional cost increases.
• Geographic Plant Expansion: Prior western plant was discontinued due to volume; regional growth has since accelerated significantly in that corridor. Revisiting a western plant location is viable.
• M&A / Roll-Up Platform: Four-entity vertically integrated platform could anchor a regional construction materials roll-up in Central Missouri.
• Deep Mining Reserve: Primary quarry has an estimated 40 million tons of remaining aggregate using current surface methods; downward mining potential not yet explored. Long-term reserve depth adds significant option value.
MARKETING OVERVIEW
Channels: Active channels include regional billboards, company website (authentic project photography), community event participation, charitable giving programs, and 35 years of word-of-mouth relationships. No paid digital advertising or social media marketing currently utilized.
Website Observations: Functional website with authentic project photography. No evident SEO optimization or digital lead generation infrastructure. Opportunity for buyer to drive incremental private commercial business through digital marketing investment without proportional field cost increases.
ADDITIONAL CONTEXT
Owner Compensation: Active Owner Salary / Draw is stated at ~$100,000+/year; $52,000 in officer salaries P&L line; remainder in wages or year-end distributions. Year-End Bonuses / Distributions are opportunistic — $20K–$50K+ in strong years. Total comp included in add-backs is partial — officer salary stays; difference versus replacement GM cost (~$200K+) is a potential add-back.
Family Involvement: Retiring Founder (age ~70, fully retired from operations) still receives ~$200,000/year in combined compensation (salary, vehicle, fuel, insurance, misc.) from the main operating entity. This is a 100% clean add-back post-sale and will continue until close. Two cousins (early 40s) are employed and considered key staff; expected to stay through transition if management approach is reasonable. Primary quarry has a broader ownership group (family investors); all parties must consent to a quarry sale. Confirm consent and structure early.
Transition Plan: Owner is 48 years old and not in a rush. Open to consulting or working for even several years post-close. Has explicitly modeled his ideal transition after an industry peer who stayed on for 3 years. A buyer who preserves the existing team structure, does not radically alter operations, and offers a structured consulting arrangement is best positioned to close and retain operational continuity.
DEAL NOTES
• Ownership Structure Complexity: Primary quarry (higher revenue, 185-year lease) has multiple family member minority owners. All must consent to sale. Verify structure and consent requirements early.
• Secondary Quarry Lease Expiration: 19 years remaining. Seller pursuing extension. Make extension a condition of closing or negotiate price adjustment if not obtained.
• 2024 Loss Year: Construction company reported ($550K) net loss. Driven by election-year revenue decline and internal intercompany asset transfers — not reflective of ongoing performance. Request accountant memo explaining transfers.
• Founder Compensation Documentation: ~$200K/year flows through P&L across multiple line items. Document all components with accountant for clean add-back in QoE.
• Main Office Not Included: Family land will not transfer. Verify alternative office operational continuity plan and confirm other facility capacity.
• Supply Chain Integration: All four entities interdependent. Partial sale creates aggregate supply or pricing risk. Negotiate supply agreements as condition if any entity is excluded.
• Asphalt Seasonality: Evaluate on annual or trailing-twelve-month basis. Q1/H1 will materially understate performance. YTD reporting is misleading for this business type.
• State Highway Work Absence: Current owner avoids MoDOT work by design. Buyer expanding into state contracts needs bonding capacity, compliance infrastructure, and crew scale.
• Estimating Dependency: Owner handles ~40% of bidding. Knowledge transfer plan and transition of estimating responsibility is a priority diligence item.
• Bonding Capacity: Performance bonds required for public projects. Verify bonding transferability or new buyer qualification as part of LOI/close conditions.
OPERATIONS
Employee Overview: ~40–50 total employees across all entities. Construction company: 20–26 (seasonal, some farm in winter).
Primary quarry: 6 FT. Secondary quarry: 4 FT. Concrete plant: 7 FT. Shared mechanics: 2 FT + 1 PT (recently retired, works 2–3 days/week by choice). Scale house operated remotely by single attendant covering both quarry locations.
Compensation: Supervisors earn six figures. Prevailing wage projects pay laborers $35–$55/hour and operators up to $68/hour. Company pays above-market; year-end bonuses distributed in strong years.
Key Operators: The Primary Quarry Lead is a multi-discipline expert — asphalt plant operator, electrician, welder, and fabricator — described as the brains of the operation, with high retention likelihood. The Primary Quarry Operations Lead keeps production moving and people organized. The Secondary Quarry Manager runs day-to-day production and personnel. Two Construction Supervisors run day-to-day operations of all construction crews.
Business Dependency on Owner: Moderate. Key risks if owner departs include estimating/bidding (~40% done by owner), cross-entity supply chain coordination, key government and vendor relationships, and pricing strategy.
Mitigation: Owner open to multi-year transition/consulting; supervisors run each site independently; strong operational team in place.
Systems & SOPs: QuickBooks-based accounting, entity-level. Remote scale house management system (camera + ticketing). Estimating mix of owner-led and estimator-supported. No formal CRM identified. SOPs are largely informal — opportunity for buyer to implement standardization during transition.
ASSETS
• Asphalt & Construction equipment: ~$2,500,000 (asphalt plant, pavers, rollers, dump trucks, service trucks, trailers).
• Primary Rock Quarry equipment: ~$1,000,000 (crusher, screens, loaders, quarry equipment). New cone crusher added 2025. Three-phase electric infrastructure established.
• Secondary Rock Quarry equipment: ~$1,000,000 (crusher, loaders, quarry equipment).
• Concrete Plant: 12 mixer trucks ($40K–$70K each); 2 loaders (~$30K each); plant/controls (~$200K). Total hard equipment: ~$800K–$900K per seller.
•Concrete Plant Property (Owned): 18 acres. Estimated value $450K–$540K at ~$25K–$30K/acre. Private well. County jurisdiction only (less restrictive). Seller price for concrete entity (land + equipment + business): $3.2M–$3.5M.
• Primary Quarry Lease: 185 years remaining. 3% royalty per ton sold. Exceptional long-term asset.
• Secondary Quarry Lease: 19 years remaining. 3% royalty per ton. Extension actively being pursued — critical milestone before sale.
• Main HQ: NOT included. Family land will not transfer. Alternative office space available at other company locations.
• Inventory as of 12/31/25 balance sheet: Primary Quarry Rock Inventory $47,364; Secondary Quarry Rock Inventory $40,576; Asphalt Inventory $151,850.
GROWTH OPPORTUNITIES
• State Highway Contract Access: Current owner avoids MoDOT/state work. Asphalt plant is capable. The I-70 widening project (4 to 6 lanes, Kansas City to St. Louis, underway through 2032–2034) represents a generational infrastructure spend in the company's region. A buyer willing to manage state contract compliance could access this market.
• Asphalt Material External Sales: Plant currently produces for internal use only. Selling mix to other contractors is untapped revenue. Plant has unused summer capacity.
• Quarry Volume Growth: Both quarries show year-over-year volume growth. With large contractors committed to regional infrastructure projects, external aggregate demand is rising.
• Pricing Optimization & Digital Marketing: No CRM or digital marketing exists. Data-driven pricing and systematic customer acquisition could drive incremental revenue without proportional cost increases.
• Geographic Plant Expansion: Prior western plant was discontinued due to volume; regional growth has since accelerated significantly in that corridor. Revisiting a western plant location is viable.
• M&A / Roll-Up Platform: Four-entity vertically integrated platform could anchor a regional construction materials roll-up in Central Missouri.
• Deep Mining Reserve: Primary quarry has an estimated 40 million tons of remaining aggregate using current surface methods; downward mining potential not yet explored. Long-term reserve depth adds significant option value.
MARKETING OVERVIEW
Channels: Active channels include regional billboards, company website (authentic project photography), community event participation, charitable giving programs, and 35 years of word-of-mouth relationships. No paid digital advertising or social media marketing currently utilized.
Website Observations: Functional website with authentic project photography. No evident SEO optimization or digital lead generation infrastructure. Opportunity for buyer to drive incremental private commercial business through digital marketing investment without proportional field cost increases.
ADDITIONAL CONTEXT
Owner Compensation: Active Owner Salary / Draw is stated at ~$100,000+/year; $52,000 in officer salaries P&L line; remainder in wages or year-end distributions. Year-End Bonuses / Distributions are opportunistic — $20K–$50K+ in strong years. Total comp included in add-backs is partial — officer salary stays; difference versus replacement GM cost (~$200K+) is a potential add-back.
Family Involvement: Retiring Founder (age ~70, fully retired from operations) still receives ~$200,000/year in combined compensation (salary, vehicle, fuel, insurance, misc.) from the main operating entity. This is a 100% clean add-back post-sale and will continue until close. Two cousins (early 40s) are employed and considered key staff; expected to stay through transition if management approach is reasonable. Primary quarry has a broader ownership group (family investors); all parties must consent to a quarry sale. Confirm consent and structure early.
Transition Plan: Owner is 48 years old and not in a rush. Open to consulting or working for even several years post-close. Has explicitly modeled his ideal transition after an industry peer who stayed on for 3 years. A buyer who preserves the existing team structure, does not radically alter operations, and offers a structured consulting arrangement is best positioned to close and retain operational continuity.
DEAL NOTES
• Ownership Structure Complexity: Primary quarry (higher revenue, 185-year lease) has multiple family member minority owners. All must consent to sale. Verify structure and consent requirements early.
• Secondary Quarry Lease Expiration: 19 years remaining. Seller pursuing extension. Make extension a condition of closing or negotiate price adjustment if not obtained.
• 2024 Loss Year: Construction company reported ($550K) net loss. Driven by election-year revenue decline and internal intercompany asset transfers — not reflective of ongoing performance. Request accountant memo explaining transfers.
• Founder Compensation Documentation: ~$200K/year flows through P&L across multiple line items. Document all components with accountant for clean add-back in QoE.
• Main Office Not Included: Family land will not transfer. Verify alternative office operational continuity plan and confirm other facility capacity.
• Supply Chain Integration: All four entities interdependent. Partial sale creates aggregate supply or pricing risk. Negotiate supply agreements as condition if any entity is excluded.
• Asphalt Seasonality: Evaluate on annual or trailing-twelve-month basis. Q1/H1 will materially understate performance. YTD reporting is misleading for this business type.
• State Highway Work Absence: Current owner avoids MoDOT work by design. Buyer expanding into state contracts needs bonding capacity, compliance infrastructure, and crew scale.
• Estimating Dependency: Owner handles ~40% of bidding. Knowledge transfer plan and transition of estimating responsibility is a priority diligence item.
• Bonding Capacity: Performance bonds required for public projects. Verify bonding transferability or new buyer qualification as part of LOI/close conditions.
CONFIDENTIAL DEAL ROOM — AUTHORIZED ACCESS ONLY
This portal and its contents are provided solely for approved members and qualified parties. Do not copy, forward, screenshot, download, or share any deal information without prior written permission. All inquiries will be handled confidentially.
CONFIDENTIAL MATERIAL - INDEPENDENT DILIGENCE REQUIRED
© 2026 Blue Collar Millionaire. All rights reserved.
BCM Private Deal Room is not a broker-dealer or investment advisor. All transactions are made at the member's own risk.